
Input tax apportionment applies when a GST-registered business makes both taxable and exempt supplies and cannot claim all its input tax in full. The De Minimis Rule/claiming-gst-(input-tax)/claiming-input-tax-incurred-to-make-exempt-supplies) sets two thresholds: average exempt supplies of $40,000 or less per month, and exempt supplies of 5% or less of total supplies. Directly attributable input tax is claimed in full where allowed, while residual input tax must be apportioned using a prescribed formula, with an annual wash-up required.
TL;DR:
- Businesses that meet both the $40,000 average exempt supply threshold and the 5% exemption ratio can claim all input tax on exempt supplies without apportionment.
- If either threshold is breached, residual input tax must be apportioned based on the ratio of taxable to total supplies, with careful exclusions for specific supply types.
- Directly attributable input tax on costs supporting only one supply type can be fully claimed, but certain expenses like motor cars are blocked regardless of attribution.
- Proper documentation, periodic reconciliation, and applying for special methods or SRP support accurate treatment and reduce IRAS audit risk.
- The De Minimis rules and apportionment calculations should be reviewed at least quarterly and during the annual wash-up to prevent errors and penalties.
Table of Contents
- How to check the De Minimis Rule and apply it in practice
- How to identify directly attributable input tax, with clear examples
- Residual input tax: the standard apportionment method and calculation steps
- When to use special apportionment methods and how SRP works
- Record keeping and the annual wash-up (longer period adjustment)
- Common mistakes and audit red flags with input tax apportionment
- Worked example: full walkthrough of De Minimis, attribution and apportionment
- Bizsquare practical checklist and spreadsheet layout for apportionment
- Author perspective on conservative recovery and practical risk management
- Bizsquare services: GST advisory, filing and IRAS audit support
- Sources
- FAQ
How to check the De Minimis Rule and apply it in practice
The De Minimis Rule decides whether a business can treat all its exempt input tax as though it related to taxable supplies. According to IRAS, the rule has two separate tests, and both must pass.
Statistic: The De Minimis Rule requires average exempt supplies of no more than $40,000 per month, and exempt supplies of no more than 5% of total supplies for the period under review. Meeting both conditions lets a business claim exempt-related input tax as if it were fully attributable to taxable supplies, subject to the usual conditions.
Here is how the two tests work in sequence:
- Calculate total exempt supplies for the prescribed accounting period, then divide by the number of months in that period to get the monthly average.
- Compare that average against $40,000. If it exceeds this figure, the business fails the first test and must apportion.
- Calculate exempt supplies as a percentage of total supplies for the same period.
- Compare that percentage against 5%. Both this test and the monthly average test must be satisfied.
- For businesses using a longer period, such as an annual filer, run the same two calculations using the full longer period figures rather than a single quarter.
Certain items are excluded from these calculations. Reverse charge supplies, out-of-scope supplies made under section 21(3) relief, and certain exempt supplies specifically carved out by the Goods and Services Tax (General) Regulations 1993 are generally kept out of the numerator and denominator, depending on the exact supply type. This is where many businesses in Singapore go wrong, because reverse charge transactions look like ordinary purchases on the ledger but are treated differently for this test.
When both thresholds are met, the outcome is straightforward. All input tax incurred in making exempt supplies is treated as though it were incurred for taxable supplies, and it becomes fully claimable, subject to the usual input tax rules. When either threshold is breached, the business moves to apportionment for its residual input tax, which is covered in the next section.
How to identify directly attributable input tax, with clear examples
Directly attributable input tax is the input tax you can trace to a specific type of supply without guesswork. If a cost relates wholly to a taxable supply, the GST on it is claimable in full, subject to the normal rules. If it relates wholly to an exempt supply, and the De Minimis Rule is not satisfied, that GST is not claimable at all.
Common examples in Singapore businesses include:
- Legal fees for drafting a taxable sale agreement, directly attributable to that taxable supply.
- Brokerage fees paid on an exempt sale of shares, directly attributable to the exempt supply.
- Delivery charges for goods sold under a taxable contract, directly attributable to taxable output.
- Interest expense on a loan used solely to fund an exempt financial activity, directly attributable to the exempt supply.
Some input tax is disallowed regardless of attribution. Regulations 26 and 27 of the Goods and Services Tax (General) Regulations 1993 block claims on items such as club subscriptions, medical expenses for staff in certain circumstances, and motor cars, even when the underlying supply is taxable. Businesses should keep supporting invoices and contracts that show the specific purpose of each cost, because this documentation is what IRAS will ask for during a review.
A few checks reduce the risk of misclassification. Review each invoice against the supply it funded, not just against the department that raised the purchase order. Flag any cost that supports more than one type of supply, since these usually belong in the residual pool rather than being forced into a single category. Cross-check treatment against capital allowance rules where a purchase might also affect income tax treatment.
Pro Tip: Tag every invoice at the point of entry with the supply type it supports, rather than trying to reconstruct attribution months later at filing time.
Residual input tax: the standard apportionment method and calculation steps
Residual input tax is GST on costs that support both taxable and exempt supplies together, such as general office rent, audit fees, or shared administrative costs. Because these costs cannot be traced to one supply type, IRAS requires a formula-based apportionment, described in the GST: Partial Exemption and Input Tax Recovery e-tax guide.
The standard method calculates a recovery rate using the ratio of taxable supplies to total supplies, then applies that rate to the residual input tax pool. The steps are as follows:
- Total the value of taxable supplies made in the prescribed accounting period, including zero-rated supplies.
- Total the value of all supplies made in the same period, taxable and exempt combined.
- Divide taxable supplies by total supplies to get the apportionment percentage, rounded to two decimal places.
- Apply that percentage to the residual input tax pool to find the recoverable amount.
- Add the recoverable residual amount to the fully attributable taxable input tax already claimed, to get the total claim for the period.
Certain supplies are excluded from both numerator and denominator before the ratio is calculated. These include supplies subject to customer accounting, reverse charge supplies, and certain supplies made to overseas persons under out-of-scope treatment. Leaving these in by mistake inflates or deflates the recovery rate and is a common source of errors picked up during IRAS reviews.
Two edge cases deserve attention. Where the denominator would be zero, such as a business with no supplies in a start-up period, IRAS guidance points businesses towards using figures from an alternative period or applying for a special method instead. Where a business changes its accounting period partway through the year, the numerator and denominator must be drawn from matching periods, never mixed across a quarter and a longer period.
The table below sets out a simple illustration of how the ratio converts into a claimable amount.
In this illustration, the business divides $900,000 by $1,000,000 to reach a 90% recovery rate, then applies that rate to the $10,000 residual pool, giving $9,000 as the claimable portion. The remaining $1,000 is treated as a cost of making exempt supplies and is not recoverable. This calculation repeats every prescribed accounting period, with a final reconciliation at the longer period wash-up.
When to use special apportionment methods and how SRP works
The standard method assumes that the ratio of taxable to total supplies fairly reflects how residual costs are actually used. For some businesses, that assumption does not hold, and IRAS allows alternative approaches under the GST Guide on attribution of input tax.
Special methods that businesses may consider include:
- Transaction count methods, useful for businesses with a high volume of small exempt transactions relative to value.
- Floorspace methods, useful where premises are physically divided between taxable and exempt activities.
- Sectoral methods, useful for businesses running genuinely separate divisions with different supply mixes.
- Output-based methods, useful where output values better reflect actual cost usage than the standard input ratio.
A Specified Recovery Percentage, referred to as SRP, lets an approved business apply one fixed percentage across future periods instead of recalculating the ratio every time. This reduces administrative work, though professional advisers note that businesses still need solid historic data to support the application and to defend the percentage if queried later.
IRAS typically expects supporting documentation covering several years of supply data, an explanation of why the standard method produces an unfair result, and a proposed alternative method with worked calculations. Businesses should treat the application as a formal submission, not a quick request, and expect a review period before a decision is issued.
Pro Tip: Apply for a special method or SRP well before your financial year end, since IRAS review timelines mean a mid-year application rarely resolves in time for that year’s wash-up.
Record keeping and the annual wash-up (longer period adjustment)
Every apportionment calculation made during the year is provisional until the longer period adjustment, commonly called the wash-up, is completed. This reconciles the whole year’s figures against the estimates used quarter by quarter.
Records businesses should keep include:
- A worksheet showing the De Minimis calculation for each prescribed accounting period and for the longer period.
- Copies of all invoices supporting directly attributable claims, organised by supply type.
- The apportionment percentage calculation for each period, with source figures for taxable and total supplies.
- A reconciliation showing the difference between provisional claims and the final wash-up figure.
- Records should generally be retained for five years, in line with standard GST record-keeping practice.
To perform the wash-up, recalculate the apportionment percentage using full-year figures instead of period-by-period estimates, then compare the resulting recoverable amount against what was actually claimed across the year. Any shortfall is claimed as an additional adjustment, and any excess is repaid, both reported in the GST return covering the final period of the longer period.
A few practical habits reduce errors at this stage:
- Reconcile provisional claims monthly rather than waiting until year end, so the wash-up is a check rather than a surprise.
- Keep invoice records aligned with the invoice requirements IRAS expects for GST purposes.
- Build a simple spreadsheet with separate columns for taxable, exempt and residual costs, updated every filing cycle.
- Flag any period where the apportionment percentage shifts by more than a few points from the prior period, since this often signals a classification issue.
Common mistakes and audit red flags with input tax apportionment
Misclassification is the most frequent trigger for IRAS queries. Businesses often place a cost in the residual pool when it was actually directly attributable, or vice versa, which distorts the recovery rate in either direction.
Incorrect handling of reverse charge and customer accounting supplies is another recurring issue. These should generally be excluded from the apportionment ratio, yet they often appear in general ledger exports without a clear tag, so they slip into the calculation unnoticed.
Inadequate documentation for the longer period adjustment causes problems during reviews, particularly where a business cannot show how its provisional quarterly claims reconciled to the final wash-up figure.
A short pre-filing checklist helps catch these issues before submission:
- Confirm every residual cost genuinely supports more than one supply type.
- Exclude reverse charge and out-of-scope supplies from both the numerator and denominator.
- Match the wash-up reconciliation to the actual GST returns filed for the year.
- Retain source invoices for every directly attributable claim above a set internal threshold.
Pro Tip: Run a dry reconciliation of your wash-up two months before year end, so any correction can still be reflected in that year’s final return.
Worked example: full walkthrough of De Minimis, attribution and apportionment
Consider a services business in Singapore with the figures below for a prescribed accounting period, used here purely as an illustration.
The steps to work through this example are as follows.
- Calculate the monthly average exempt supplies. For a quarter, divide $30,000 by three months, giving $10,000 a month, which is below the $40,000 monthly threshold.
- Calculate exempt supplies as a percentage of total supplies. $30,000 divided by $880,000 gives roughly 3.4%, below the 5% threshold.
- Since both De Minimis conditions are met, the $2,000 of directly attributable exempt input tax becomes fully claimable, alongside the $40,000 directly attributable taxable input tax.
- Because De Minimis is satisfied, the residual input tax of $12,000 does not need the standard apportionment calculation at all, and the full amount is claimable in this scenario.
If the exempt supplies had instead been $60,000 for the quarter, the monthly average would breach $40,000, forcing apportionment. The business would then calculate its recovery percentage by dividing taxable supplies by total supplies, and apply that percentage to the $12,000 residual pool, exactly as shown in the earlier apportionment section. This is why running the De Minimis check first, before touching the residual formula, saves unnecessary work every period.
Bizsquare practical checklist and spreadsheet layout for apportionment
Before each GST filing, run through a short sequence: confirm the De Minimis result, tag every cost by supply type, and reconcile the residual pool separately from directly attributable items.
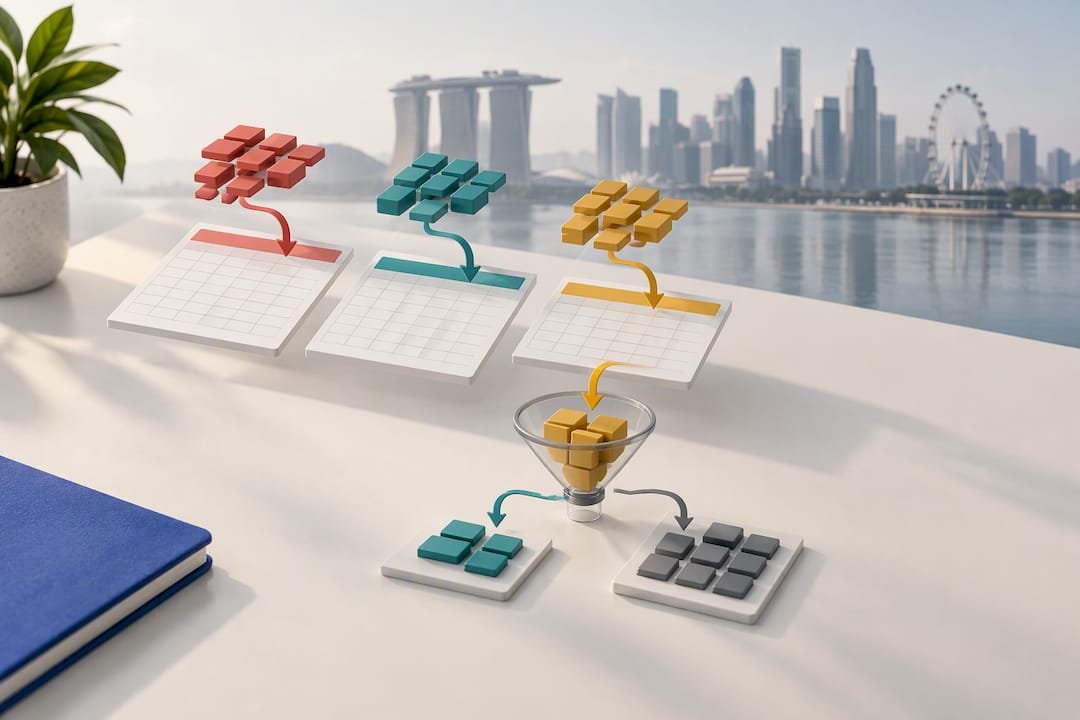
A practical spreadsheet layout uses separate columns for taxable supplies, exempt supplies, directly attributable input tax by type, and residual input tax, with a formula cell calculating the apportionment percentage automatically each period.
Escalate to professional advisory or consider an IRAS ruling when a cost genuinely defies clean classification, or when the standard method consistently produces a result that does not match how the business actually operates.
- Reviews apportionment worksheets as part of GST filing and advisory work for SMEs.
- Supports businesses through IRAS audit queries and dispute resolution when apportionment is challenged.
- Assists with cloud accounting setup to ensure classification tags are captured automatically at the point of entry.
Pro Tip: Ask an adviser to check your apportionment formula cells once a year, since a small formula error can compound across every filing period.
Author perspective on conservative recovery and practical risk management
Input tax apportionment rewards caution more than cleverness. A well-documented, conservative claim survives an IRAS review far better than an aggressive one built on thin records. Special methods and SRP can genuinely help businesses with unusual supply mixes, but only when the supporting data is solid enough to defend on request. The most useful habit is a periodic internal review, run well ahead of the annual wash-up, rather than a scramble at year end.
— Vandro
Bizsquare services: GST advisory, filing and IRAS audit support
Getting input tax apportionment right takes ongoing attention, not a once-a-year calculation. Bizsquare Accounting helps GST-registered businesses in Singapore review their apportionment worksheets, apply the De Minimis Rule correctly, and prepare for the annual wash-up with confidence.
Bizsquare’s team handles the technical detail so your finance staff can focus on running the business, drawing on services including:
- GST Filing & Advisory for periodic returns and apportionment reviews.
- Corporate Tax Filing & Advisory covering the wider tax position alongside GST.
- Accounting and Bookkeeping Services to keep supply and input tax records audit-ready throughout the year.
- IRAS Audit Support & Dispute Resolution for businesses facing a query on a past apportionment claim.
If your business makes both taxable and exempt supplies, get in touch through the corporate tax filing and advisory page for a review of your current apportionment approach.
Sources
These are the primary sources behind the rules covered above, useful for businesses that want to check the original wording before filing.
- Goods and Services Tax (General) Regulations 1993 — Regulation 28, Singapore Statutes Online
- Alternate methods to calculate GST input tax recovery, Deloitte
FAQ
What is input tax in Singapore?
Input tax is the GST a business pays on its purchases and expenses, which it can generally reclaim from IRAS if the purchases relate to taxable supplies. It cannot usually be reclaimed against exempt supplies unless the De Minimis Rule is satisfied.
What is the formula for input tax apportionment?
The standard formula divides taxable supplies by total supplies for the period to get a recovery percentage, then applies that percentage to the residual input tax pool. This calculation is described in detail in the IRAS partial exemption guide.
Is input tax an asset or liability?
Input tax recoverable from IRAS is treated as an asset, usually recorded as a GST receivable on the balance sheet until refunded or offset against output tax. Input tax that fails the attribution or De Minimis tests becomes a cost rather than an asset, since it cannot be recovered.
Can you claim input tax on exempt supplies?
Generally, input tax on exempt supplies is not claimable, but the De Minimis Rule allows a full claim when average exempt supplies stay at or below $40,000 a month and exempt supplies stay at or below 5% of total supplies. If either threshold is breached, only the apportioned share of residual input tax is claimable.
How often does a business need to check the De Minimis Rule?
The De Minimis test should be checked for every prescribed accounting period and again at the longer period wash-up, since provisional results during the year may change once full-year figures are reconciled. Businesses filing quarterly typically run this check four times a year, plus once at the annual wash-up.
What happens if apportionment is calculated incorrectly?
An incorrect apportionment can lead to an overclaim or underclaim of input tax, which IRAS may adjust on review, sometimes with penalties for material errors. Keeping clear worksheets and source documentation, as described in the IRAS attribution guide, helps businesses correct errors before they become disputes.