
A chart of accounts is the master list of ledger accounts that records every transaction a business makes. Singapore SMEs should confirm their applicable reporting framework, whether full SFRS or SFRS for Small Entities, before finalising codes, since this choice shapes how accounts are grouped and disclosed. Once confirmed, adopt a simple numbered template and build GST mapping into the structure from day one.
TL;DR:
- Use four-digit codes within specific ranges for each classification, leaving gaps for future expansion and making adjustments across financial years simple.
- Separate GST-related accounts into distinct categories for output, input, zero-rated, and exempt supplies to streamline GST reporting and reconciliation.
- Confirm your reporting framework early, as it influences the level of disclosure needed and ensures your chart of accounts stays compatible with future system changes.
- Keep detailed records for at least five years and store backups in multiple locations, including offsite or cloud systems, to comply with IRAS regulations.
- Build your chart of accounts with automation and InvoiceNow compatibility in mind, to facilitate GST filing, reduce manual work, and support future growth.
Table of Contents
- What is a chart of accounts and its five main classifications
- Recommended numbering system for Singapore SMEs
- Sample chart of accounts for a Singapore services company
- Design principles for a Singapore SME chart of accounts
- Mapping the CoA to GST, InvoiceNow and reporting frameworks
- Record keeping and retention rules under IRAS
- Practical template, quick setup checklist and Bizsquare support
- Why your chart of accounts needs to be built for tomorrow
- How Bizsquare Accounting can help implement and maintain your CoA
- FAQ
- Sources
What is a chart of accounts and its five main classifications
A chart of accounts organises every entry in the general ledger into named, numbered categories, so transactions flow consistently into the balance sheet and profit and loss statement. Each account represents a specific type of financial activity, and together they form the backbone of a company’s Singapore accounting framework.
Most accounting systems group accounts into five classifications:
- Assets: cash, bank balances, trade receivables, fixed assets and inventory.
- Liabilities: trade payables, GST payable, loans and accrued expenses.
- Equity: share capital, retained earnings and director’s current account.
- Revenue: service fees, product sales and other operating income.
- Expenses: rent, salaries, professional fees and utilities.
Accurate classification matters because IRAS reviews how figures are reported in your financial statement accounts during corporate tax filing. A miscoded expense or revenue line can distort your taxable income and cause avoidable queries during assessment.
Recommended numbering system for Singapore SMEs
A clear numbering system keeps your chart of accounts Singapore structure consistent as the business grows, and most cloud platforms expect a numeric range per classification.
- Use four-digit codes as a starting point, since they allow room to expand without renumbering later.
- Assign assets to the 1000 to 1999 range, covering cash, receivables and fixed assets.
- Assign liabilities to 2000 to 2999, including trade payables and GST payable.
- Assign equity to 3000 to 3999, revenue to 4000 to 4999, and cost of sales to 5000 to 5999.
- Place operating expenses in 6000 to 6999, and reserve 7000 to 8999 for other income, finance costs and tax accounts.
- Leave gaps of ten between related accounts, so you can insert new sub-accounts without disturbing the sequence.
- Reserve a block of codes for departments, branches or projects if you expect to track performance separately.
- Keep the same numbering scheme across financial years, since changing codes midstream complicates comparative reporting.
This structure works comfortably with popular platforms used for setting up accounts Singapore businesses typically choose, including Xero, QuickBooks and MYOB, all of which accept custom numeric ranges during setup.
Sample chart of accounts for a Singapore services company
Below is a copy-ready template suited to a typical services business, such as a consultancy or agency. Adjust the detail to match your own operations, but keep the classification logic intact.
- 1010 Cash on hand: petty cash held at the office.
- 1020 Bank, DBS current account: main operating account.
- 1200 Trade receivables: invoices issued but not yet collected.
- 1500 Computer equipment: laptops, monitors and office hardware.
- 2010 Trade payables: supplier invoices awaiting payment.
- 2200 GST payable: output tax collected on taxable supplies.
- 2300 CPF payable: employer and employee contributions due.
- 3000 Share capital: amount subscribed by shareholders.
- 3100 Retained earnings: accumulated profit carried forward.
- 4000 Service revenue: consulting or project fees billed to clients.
- 5000 Subcontractor costs: direct costs tied to delivering client work.
- 6010 Salaries and CPF: staff remuneration and statutory contributions.
- 6050 Rent and utilities: office premises and related charges.
- 6080 Professional fees: accounting, legal and corporate secretarial costs.
- 7000 Interest income: bank deposit interest earned.
- 8000 Corporate tax expense: provision for income tax payable.
A trading business adds inventory and cost of goods sold accounts under the 1000 and 5000 ranges, while an F&B operator typically splits cost of sales between food, beverage and packaging to track margins by category. These COA examples Singapore businesses adopt should always reflect how the owner actually reviews performance, not just how the bookkeeper files tax.
Design principles for a Singapore SME chart of accounts
Design your CoA around how you want to read your numbers, not only around statutory filing. A chart built purely for compliance often fails to answer the questions owners actually ask about margins, cash flow or department performance.
- Name accounts in plain, specific terms, such as “Marketing, digital ads” rather than a vague “Marketing expense”.
- Use contra accounts, like accumulated depreciation, to keep gross and net values visible side by side.
- Create cost centres or sub-accounts only when a business genuinely tracks separate departments or projects.
- Assign one person to own the chart of accounts and document every change with a reason and date.
Pro Tip: Review your chart of accounts once a year, and whenever you switch accounting software or add a new revenue line.
A coherent chart of accounts anchors management reporting, forecasting and automation, and should serve future reporting needs as well as present-day compliance, according to commentary from EY Singapore. That principle holds whether you run a two-person consultancy or a growing trading company.
Mapping the CoA to GST, InvoiceNow and reporting frameworks
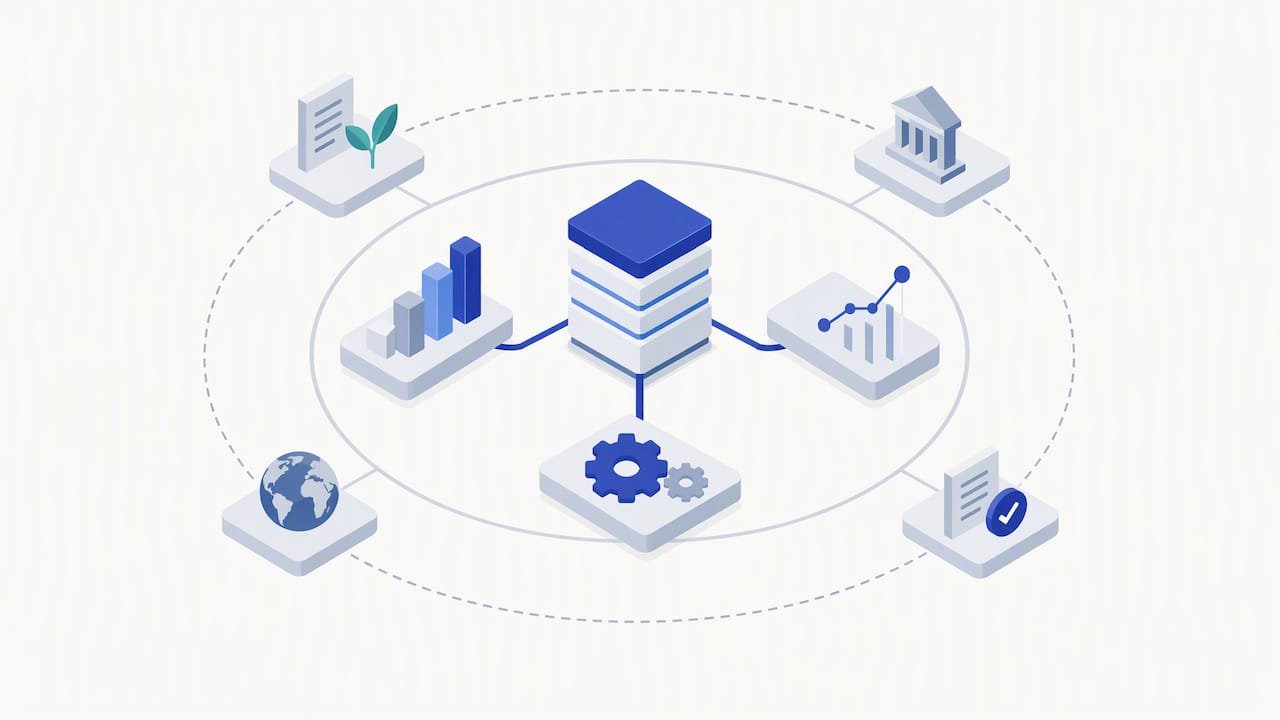
GST reporting works best when the chart of accounts separates tax categories clearly, rather than lumping them into one generic tax code.
- Create distinct accounts for output GST, input GST, zero-rated supplies, exempt supplies and out-of-scope transactions.
- Add a separate line for disallowed input tax, so it never accidentally offsets your claimable GST.
- Keep a GST adjustments or suspense account to park corrections before month-end filing.
InvoiceNow, the national e-invoicing network built on the Peppol standard, changes how invoice data flows into your accounts. IRAS accepts InvoiceNow invoices as valid GST tax invoices when they contain the required details, and mapping your GST account codes to Peppol fields reduces manual reconciliation at filing time. Before you finalise any account structure, confirm which accounting system Singapore framework applies to your company.
A fact worth noting: ACRA announced amendments extending reduced-disclosure benefits under FRS 119, which means the reporting standard you follow can change the disclosure detail your chart of accounts needs to support. Confirming your framework early avoids restructuring accounts later.
Record keeping and retention rules under IRAS
IRAS requires companies to retain accounting records and source documents for at least five years from the relevant Year of Assessment. This applies to invoices, receipts, bank statements and payroll records, whether stored on paper or electronically.
- Keep electronic copies in a system that allows retrieval by date, invoice number or account code.
- Store backups in at least two locations, including one offsite or cloud-based copy.
- When migrating accounting systems, keep an old-to-new account mapping table and run parallel reports for one full cycle before closing the old system.
Our guide on bookkeeping accuracy for Singapore SMEs covers practical reconciliation habits that complement these retention rules.
Practical template, quick setup checklist and Bizsquare support
Setting up a chart of accounts is straightforward once you follow a sequence, rather than trying to build everything at once.
- Confirm your reporting framework, SFRS or SFRS for Small Entities, before assigning any account codes.
- Copy the sample chart of accounts above and adjust it to match your actual revenue lines.
- Enter opening balances for every account, matching your most recent financial statements.
- Map historic transactions into the new structure, checking GST categories carefully.
- Run a trial report and review it against last year’s figures before going live.
Common pitfalls include mismatched tax codes, incorrect opening balances and confusion when running multiple entities under one bookkeeping system. Our small business accounting checklist walks through these steps in more detail.
Business management consultancies support Singapore SMEs through accounting and bookkeeping services, cloud accounting setup using Xero, QuickBooks or MYOB, and ongoing corporate tax filing and advisory once your chart of accounts is live.
Why your chart of accounts needs to be built for tomorrow
A chart of accounts built only for today’s compliance deadline rarely survives a system change or a new revenue stream without costly rework. Plan your account codes with InvoiceNow and automation in mind from the outset, and keep governance light but genuinely enforceable, reviewing the structure whenever your systems or reporting framework shift.
— Vandro
How Bizsquare Accounting can help implement and maintain your CoA
Setting up a chart of accounts correctly the first time saves you from costly restructuring later, and that is exactly where Bizsquare Accounting’s Accounting and Bookkeeping Services make a practical difference. Our team maps your business accounts chart to the right reporting framework, builds GST categories that match InvoiceNow requirements, and sets up your chosen cloud platform correctly from day one.
- Cloud Accounting Setup: configuration of Xero, QuickBooks or MYOB with your custom chart of accounts.
- Accounting and Bookkeeping Services: ongoing bookkeeping, reconciliations and financial statement preparation.
- Corporate Tax Filing & Advisory: GST filing support and account mapping for tax accuracy.
- Corporate Advisory & Outsourced CFO Services: ongoing review of your reporting structure as the business grows.
For companies also weighing financing options, our partner guide on SME loans in Singapore explains how clean financial statements support loan applications. When you’re ready to set up or restructure your chart of accounts properly, visit our accounting and bookkeeping services page to arrange a consultation.
FAQ
What are the 5 basic charts of accounts?
The five basic classifications are assets, liabilities, equity, revenue and expenses. Every transaction in a Singapore business ultimately falls into one of these five categories within the general ledger.
How do I create a chart of accounts?
Start by confirming your reporting framework, then list every account your business needs under the five main classifications. Assign numeric codes by range, such as 1000 to 1999 for assets, and test the structure against a recent financial statement before going live.
What are the 7 types of accounts?
Definitions vary, but a common version expands the five basic classifications to include cost of sales and other income or finance costs as separate groups. This split helps businesses track gross margin and non-operating income more clearly.
What are the 5 major classifications of accounts in the chart of accounts?
The five major classifications are assets, liabilities, equity, revenue and expenses, matching the structure used across most Singapore accounting software platforms. Each classification carries its own numeric range to keep reporting consistent.
How long must I keep accounting records in Singapore?
IRAS requires companies to retain source documents and accounting records for at least five years from the relevant Year of Assessment. This applies to both paper and electronic records.
Does my chart of accounts need to match InvoiceNow categories?
Mapping your GST accounts to InvoiceNow and Peppol fields reduces manual reconciliation, since IRAS accepts InvoiceNow invoices as valid GST tax invoices when they meet the required contents. It is not mandatory for every account, but it simplifies GST filing considerably.
Which reporting framework should my Singapore company follow?
Most small companies qualify for SFRS for Small Entities, while larger or more complex entities follow full SFRS. Confirm your eligibility through ACRA’s accounting standards guidance before finalising your chart of accounts.
Can Bizsquare help set up my chart of accounts?
Accounting and bookkeeping services and cloud accounting setups for Xero, QuickBooks and MYOB, including chart of accounts design for Singapore SMEs, are offered by some business consultancies. Pricing for these services is available upon inquiry on providers’ service pages.
Sources
- FRS 119 amendments extending reduced-disclosure benefits
- IRAS | Record keeping requirements
- It’s time to breeze through GST audits with InvoiceNow
- How the chart of accounts shapes the future of reporting | EY Singapore