
A foreign receipt can qualify for the foreign-sourced income exemption, but only when three statutory conditions are met. The income must be “subject to tax” abroad, the foreign jurisdiction’s headline tax rate must be at least 15%, and the Comptroller of Income Tax must be satisfied that the exemption is beneficial to the resident claiming it. Companies that assume automatic relief without proof usually run into trouble at review stage, so proper documentation and correct filing matter as much as the underlying facts.
TL;DR:
- Foreign-sourced dividends, branch profits, and service income can qualify for exemption if the income is taxed abroad at a rate of at least 15% and the foreign jurisdiction confirms this with supporting documents.
- Proper documentation, including tax payment receipts, dividend vouchers, audited accounts, and contracts, is essential to prove all three FSIE conditions during IRAS review.
- Claiming the exemption requires accurate declaration of the income details, jurisdiction, tax rates, and supporting schedules on Form C or C-S, with professional advice recommended for borderline cases.
- If the foreign tax rate is below 15%, companies should consider using foreign tax credits, especially since exemption is not available and expenses may be better deducted elsewhere.
- Maintaining an organized, up-to-date evidence pack for each foreign entity helps prevent delays or disputes during tax reviews, saving time and reducing compliance stress.
Table of Contents
- What counts as foreign-sourced income exemption eligible income?
- What are the three FSIE qualifying conditions?
- How is each income type assessed differently?
- What documents should you keep for an FSIE claim?
- How do you claim the exemption on Form C or Form C-S?
- Should you claim exemption or use foreign tax credit instead?
- What mistakes trigger IRAS scrutiny on FSIE claims?
- Why organised compliance pays off for company owners
- How Bizsquare helps you claim the foreign-sourced income exemption correctly
- Sources
- FAQ
What counts as foreign-sourced income exemption eligible income?
The Inland Revenue Authority of Singapore treats foreign-sourced income as income that does not arise from a trade or business carried on within Singapore. That distinction sits at the heart of how Singapore taxes companies receiving foreign income, because Singapore generally taxes on a territorial basis with a remittance twist.
Income earned locally gets taxed as it accrues. Foreign income, however, typically only becomes taxable in Singapore when it is remitted, deemed remitted, or brought into Singapore. This timing gap gives resident companies room to plan, provided the receipt falls into one of the categories IRAS recognises for exemption purposes.
Three categories qualify under the foreign-sourced income exemption scheme:
- Foreign-sourced dividends paid by a company incorporated outside Singapore
- Foreign branch profits earned through an overseas branch of a Singapore company
- Foreign-sourced service income earned from a trade, profession, or business carried on through a fixed place of operation abroad
Everything else, including foreign-sourced interest or royalties outside these categories, generally falls outside this specific exemption and gets assessed under ordinary rules.
What are the three FSIE qualifying conditions?
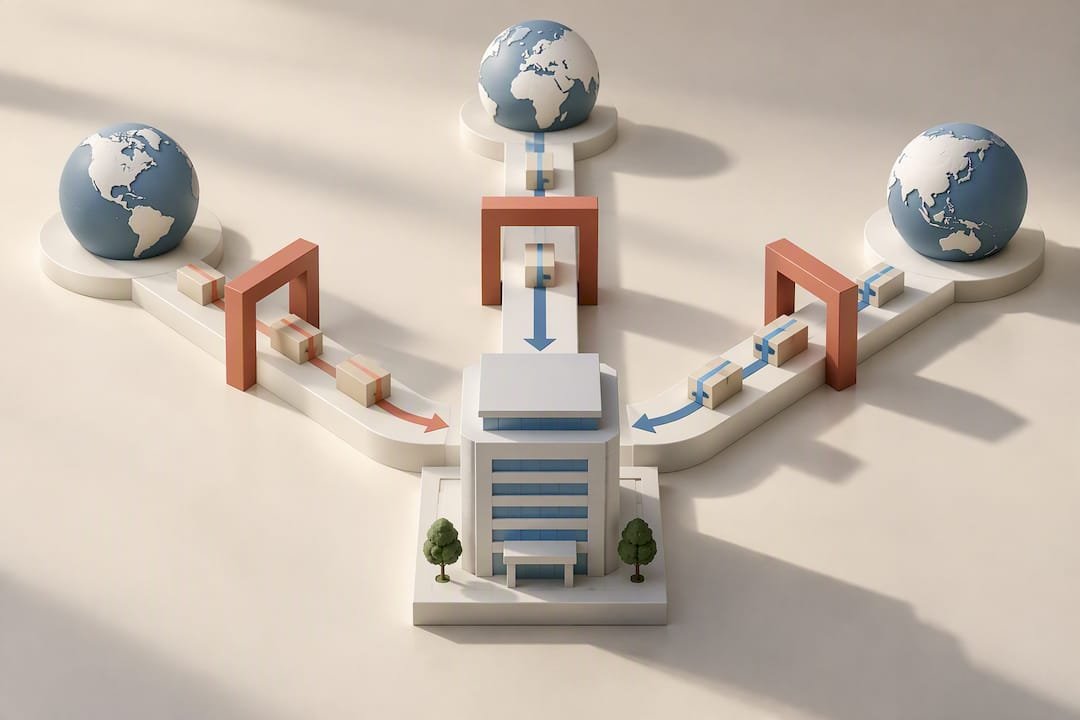
Each condition operates independently, and a claim fails if even one is not satisfied. Understanding what evidence each condition demands makes the difference between a smooth filing and a drawn out dispute.
- Subject to tax condition. The income must have suffered tax in the foreign jurisdiction where it arose. Acceptable proof includes foreign tax payment receipts, tax incentive certificates confirming a concessionary rate applied, dividend vouchers showing tax deducted, or audited accounts that clearly show current tax charged against the relevant profits.
- Foreign headline tax rate condition. The jurisdiction’s highest corporate tax rate, not the actual rate paid, must be at least 15% in the year the income arose. A company benefiting from a tax holiday in a jurisdiction with a 17% headline rate can still qualify, because the headline rate test looks at the statutory rate, not the effective one.
- Comptroller’s beneficial discretion. The Comptroller must be satisfied that granting the exemption benefits the Singapore tax resident. This is a judgement call, and companies strengthen their position by showing the remittance supports genuine business activity, reinvestment, or expansion rather than pure tax arbitrage.
IRAS guidance frames this scheme as targeted double taxation relief rather than a blanket exemption. This is exactly why each condition needs its own supporting paper trail.
Pro Tip: Check the foreign jurisdiction’s headline corporate tax rate before you remit, not after. A quick search of that country’s tax authority website, or a call to your adviser, can save weeks of back and forth with IRAS later.
How is each income type assessed differently?
Dividends, branch profits, and service income each carry their own evidence expectations, and IRAS reviewers look for slightly different paperwork depending on the category.
- Foreign-sourced dividends need proof of underlying tax paid by the paying company, typically dividend vouchers stating tax deducted at source and audited financial statements confirming the company’s tax position in its home jurisdiction.
- Foreign branch profits require a clear allocation of profit between the branch and the head office, supported by branch level accounts showing tax assessed and paid in the branch’s country.
- Foreign-sourced service income hinges on where the service was actually provided. Invoices, contracts, and proof of foreign tax paid on that income all matter, and the physical location of the work often decides the outcome.
Documentation of foreign tax paid, combined with evidence of real business activity where the income arose, frequently determines whether IRAS accepts a subject to tax claim in the first place.
What documents should you keep for an FSIE claim?
Building the right evidence pack before you file saves considerable time if IRAS ever asks questions. Advisers commonly recommend assembling this pack at the point of receipt, not months later when memories and paper trails have gone cold.
- Tax payment receipts or official tax authority statements from the foreign jurisdiction
- Dividend vouchers showing gross dividend and tax withheld or deducted
- Tax incentive certificates where a concessionary rate applied
- Audited financial statements of the paying entity or branch
- Underlying contracts and invoices for service income
- A schedule reconciling amounts remitted against amounts taxed abroad
Singapore companies must retain supporting records for at least five years from the relevant year of assessment, in line with standard record-keeping obligations for corporate tax. Building a standard reconciliation schedule that you attach to every Form C filing, rather than reinventing the wheel each year, keeps the process consistent and audit ready.
Pro Tip: Keep a single running spreadsheet per foreign entity, updated every time a dividend or profit remittance happens. It turns a stressful year-end scramble into a five minute copy and paste job.
How do you claim the exemption on Form C or Form C-S?
Claiming the foreign-sourced income exemption correctly on your corporate tax return involves more than ticking a box. IRAS expects specific data points, and missing one usually triggers a query.
- Declare the nature and amount of the foreign income in the relevant section of your tax computation.
- State the jurisdiction where the income arose and confirm its headline corporate tax rate for that year.
- Confirm that foreign tax was actually paid, attaching supporting schedules such as dividend vouchers or tax certificates.
- Attach a reconciliation showing how the exempt amount was calculated against total income received.
- Submit through Form C-S if your company qualifies under the simplified filing criteria, or Form C for companies with more complex affairs, noting that Form C generally demands fuller supporting schedules.
If your facts sit close to the boundary, particularly around the Comptroller’s beneficial discretion, it is worth seeking professional advice or, in genuinely uncertain cases, an advance ruling from IRAS before you file. A complete guide to filing corporate tax in Singapore can help you map out which schedules apply to your situation.
Should you claim exemption or use foreign tax credit instead?
Claiming exemption is not always the better outcome, and this is where many company owners leave money on the table. Expenses directly related to exempted foreign-sourced income must be allocated and deducted only against that income, not against your Singapore-sourced profits.
- If foreign tax paid was low relative to Singapore’s 17% corporate rate, foreign tax credit may leave you with a smaller residual tax bill than exemption would.
- If the foreign jurisdiction’s headline rate falls below 15%, you cannot use the exemption route at all, so foreign tax credit becomes your only relief option.
- If expenses tied to the foreign income are substantial, exemption can mean those expenses go unused for tax purposes elsewhere.
Consider a simplified example. Because the headline rate falls under the 15% threshold, exemption is not available, and claiming foreign tax credit against the Singapore tax liability on that income gives a better net position. Advisers note that companies must weigh exemption against foreign tax credit carefully, since documentation strength often decides which route actually works in practice. Our guide on effective tax saving tips for Singapore businesses covers this decision in more depth.
What mistakes trigger IRAS scrutiny on FSIE claims?
Most disputes over the foreign-sourced income exemption trace back to a handful of recurring errors, and nearly all of them are avoidable with earlier preparation.
- Assuming every foreign receipt automatically qualifies, without checking the headline tax rate first
- Providing insufficient proof of foreign tax paid, particularly relying on management accounts instead of audited statements
- Weak substance in the source jurisdiction, which undermines the Comptroller’s beneficial discretion test
- Mismatched figures between amounts remitted and amounts shown as taxed abroad
Building controls around these weak points protects your claim before it ever reaches an IRAS reviewer’s desk. Start by creating a standing evidence pack template for each foreign entity you deal with, checking headline rates before, not after, remittance, and reconciling tax paid against amounts remitted every single time money crosses the border.
Pro Tip: When relying on the Comptroller’s beneficial discretion, write a short justification memo at the time of the transaction explaining why the exemption benefits your Singapore operations. A memo written months later looks like an afterthought; one written at the time looks like genuine business reasoning.
Where a jurisdiction’s tax rules shift, for instance a country lowering its headline corporate rate below 15%, your eligibility for future remittances from that jurisdiction can change even if past claims remain valid. Keep an eye on the tax regimes of any country where your group holds subsidiaries or branches, since a rate change abroad can quietly close off relief you have relied on for years.
Why organised compliance pays off for company owners
Company owners underestimate how much a disorganised paper trail costs them, not in penalties necessarily, but in time and stress during a tax review. Structured documentation, gathered as income arrives rather than assembled retrospectively, turns what could be a weeks long IRAS query into a same day response.
Professional advisers earn their fee here in a very specific way. They know which evidence IRAS actually wants to see, they spot a weak headline rate argument before it becomes a rejected claim, and they draft the kind of beneficial discretion justification that reads as considered reasoning rather than an afterthought. For a company juggling operations, staff, and clients, that speed matters more than most owners realise until they are staring down a filing deadline with incomplete paperwork.
The foreign-sourced income exemption rewards preparation. Companies that treat documentation as a live task, updated with every remittance, consistently file cleaner returns than those who scramble each March.
— Vandro
How Bizsquare helps you claim the foreign-sourced income exemption correctly
Getting an FSIE claim right means having the right evidence, filed the right way, at the right time. Bizsquare’s Corporate Tax Filing & Advisory service builds audit-ready evidence packs for dividend, branch profit, and service income claims, then handles the Form C or Form C-S submission itself.
Beyond the filing itself, Bizsquare’s Accounting and Bookkeeping Services keep the underlying records clean throughout the year, so your dividend vouchers, audited accounts, and reconciliation schedules are ready well before filing season arrives rather than assembled in a panic. For companies weighing exemption against foreign tax credit, or deciding how to allocate expenses against exempted income, our Corporate Advisory & Outsourced CFO Services provide the strategic input that a bookkeeper alone cannot offer.
The outcome for company owners is straightforward: fewer queries from IRAS, accurate Form C submissions the first time, and reduced compliance risk on every foreign remittance you bring into Singapore. If you are unsure whether your last foreign receipt actually qualified, or want a second opinion before your next filing, get in touch with Bizsquare’s corporate tax advisory team and have your documentation reviewed before deadline pressure sets in.
Sources
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is considered foreign-sourced income?
Foreign-sourced income is income that does not arise from a trade or business carried on in Singapore, such as dividends from an overseas company, profits from a foreign branch, or service fees earned through a fixed place of operation abroad.
What foreign income is exempt from tax in Singapore?
Foreign-sourced dividends, foreign branch profits, and foreign-sourced service income can be exempt when the three FSIE conditions are met: subject to tax abroad, a foreign headline tax rate of at least 15%, and the Comptroller’s beneficial discretion. Other foreign income types, like most interest or royalties, generally do not qualify.
What types of income are exempt from tax in Singapore?
Beyond FSIE eligible foreign income, Singapore also exempts certain locally sourced income under separate schemes, such as specific dividend income and some qualifying gains. The foreign-sourced income exemption specifically covers dividends, branch profits, and service income from abroad.
What is exempt foreign employment income?
Exempt foreign employment income generally refers to income earned by individuals working overseas that falls outside Singapore’s tax net under separate personal income tax rules. This differs from the corporate FSIE scheme, which applies to company level dividends, branch profits, and service income.
How do I prove the “subject to tax” condition?
Acceptable evidence includes foreign tax payment receipts, tax incentive certificates, dividend vouchers showing tax withheld, and audited accounts confirming current tax charged. IRAS accepts that a concessionary rate under a genuine incentive scheme can still satisfy this condition.
What if the foreign jurisdiction’s tax rate is below 15%?
The exemption is not available, since the headline rate condition requires at least 15% in the year the income arose. In that situation, claiming foreign tax credit instead usually gives a better outcome.
Does FSIE apply to interest and royalty income?
No, the exemption scheme as administered by IRAS specifically covers foreign-sourced dividends, foreign branch profits, and foreign-sourced service income. Interest and royalty income generally fall outside this exemption and get assessed under standard rules.
How long must I keep FSIE supporting documents?
Companies should retain tax receipts, dividend vouchers, and related records for at least five years from the relevant year of assessment. Keeping a standing evidence pack per foreign entity makes this far easier to manage.
Can I claim FSIE on Form C-S instead of Form C?
Yes, provided your company meets the qualifying criteria for the simplified Form C-S filing. Form C generally requires fuller supporting schedules, so companies with more complex foreign income structures often need Form C instead.
What happens if IRAS rejects my exemption claim?
If a claim is rejected, the income typically gets assessed under ordinary tax rules, though foreign tax credit may still apply if foreign tax was paid. This is why building strong documentation before filing matters more than fixing gaps after a rejection.
Should I claim exemption or foreign tax credit?
It depends on the effective tax rate paid abroad compared to Singapore’s rate, and on how expenses tied to the foreign income are allocated. Advisers recommend weighing both options before filing, since documentation strength often decides which route works better.
Can Bizsquare help prepare my FSIE claim?
Yes, Bizsquare’s Corporate Tax Filing & Advisory service builds evidence packs, verifies headline tax rates, and prepares accurate Form C or Form C-S submissions for foreign-sourced income claims. For current pricing details, please refer to the Bizsquare website.
Does a tax holiday abroad disqualify my claim?
Not necessarily, since the headline rate test looks at the jurisdiction’s statutory rate, not what the company actually paid.